All Categories
Featured
The 2026 Business Climate in Arabia
Table of Contents
Dangers are tilted to the downside. In the occasion of a prolonged dispute, the existing influence on the region will be compoundedthrough raised energy and food prices, decreasing trade, tourism and remittances, increased financial pressures, and displacement. "The existing crisis is a stark suggestion of the work ahead for the area: not just to weather shocks, however to rebuild more durable economies with stronger macroeconomic fundamentals, innovate and improve governance, purchase facilities, and increase employment-creating sectors," said.
With peace and the right action, nations can develop the institutions, abilities and competitive sectors that develop chances for individuals." With this long-term vision in mind, the report takes a close take a look at the region's capacity for commercial policy government actions to increase strategic organization activity as a motorist of financial growth and job production.

Governments in the region have adopted commercial policy at a high rate in the last decade, often through sovereign wealth funds and state-owned business, however the results have been blended. The report highlights the important need for strong organizations and careful targeting of policies. "As countries deal with the heavy toll of the present dispute, it is necessary to likewise not forget the work needed for lasting peace and prosperity," said.
Driving Non-Oil Success through Strategic Diversification
Q2 2026: The ICAEW Economic Update Middle East, is a quarterly economic forecast for the area prepared straight for the financing profession. The GCC economy deals with a marked contraction this year pending details of the US-Iran arrangement to end the war. We anticipate energy flows, tourism and investor sentiment to gradually normalise as war disturbances go away.
The interim agreement between the US and Iran is a substantial step towards reaching a full-blown deal. A complete go back to normality in the Strait of Hormuz will likely take some time, however the risk of a recession-inducing oil rate spike has declined. Worldwide GDP is expected to grow by 2.4% this year, 0.2 ppt less than we forecasted 3 months back, and 3.1% in 2027.
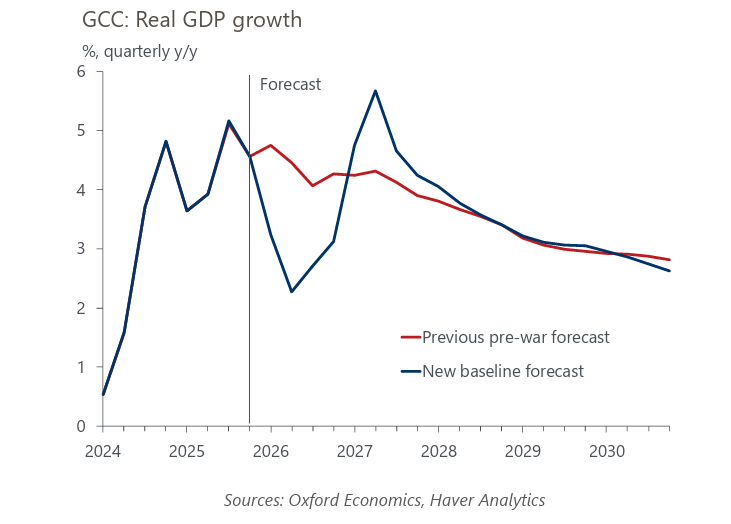
2026 Business Landscape in the GCCWe forecast a 4.1% contraction in Middle East GDP this year (versus forecasted 3.6% expansion before the war), greater than the decrease in the very first year of the Covid pandemic. Kuwait, Iran, Iraq and Qatar stand apart as the hardest hit, owing to their failure to prevent the disruption to local shipping, war-driven facilities damage and tourist losses.
Top Foreign Capital Trends within the GCC MarketOur 2026 outlook for the GCC is weaker than three months ago, with GDP projection to agreement by 2.4% compared to a 0.2% decrease forecasted formerly. We expect Oman and Saudi Arabia to be the least negatively impacted by the fallout from the conflict, with both economies continuing to expand this year.
The financial damage sustained in the last few months is considerable. Saudi GDP information for Q1 showed growth slowed to 3% y/y, with non-oil activities broadening by 2.9%, the weakest speed given that the Covid pandemic. On a seasonally adjusted basis, GDP contracted 1.2% q/q, driven by a 6.8% fall in oil activities as the Strait of Hormuz interruption hit late in the quarter.
Optimizing Capital Diversification in a Global Economy
Aside from Oman, all GCC manufacturers as well as Iran and Iraq have actually suffered extensive oil and gas production losses because the start of the conflict. May information show local production almost halved from pre-war levels, with the decrease deepening relative to March and April. Rerouting efforts, including by Saudi Arabia through the East-West Pipeline and the UAE through the Habshan-Fujairah pipeline, have helped prevent an even bigger plunge in output.
However, we anticipate GCC oil sector output to agreement by 14.5% this year, which will mark the steepest decrease in numerous years. We then anticipate a 23.5% rebound next year, driven mainly by normalisation from a badly depressed base. Oil rates have actually been unpredictable, alleviating listed below $85 per barrel as the interim arrangement was announced.
In the medium term, we expect oil prices to be somewhat lower than our pre-war baseline, as the UAE's departure from OPEC+ enables a steady increase in its output towards the 5mn barrel daily production target as soon as trade normalises. Versus this background, the UAE will speed up the building of a new West-East pipeline that must double the capacity of export through Fujairah.
The May PMI studies reported output development reaching its strongest level in three months, driven mainly by improved domestic need. They stay listed below long-run averages, with weak export orders and cost pressures from greater product and transportation expenses are a typical style. Overall, we expect a 1.1% contraction in GCC non-energy sectors this year (compared to 4.2% development pre-war) and a gradual recovery over the rest of the decade.

Latest Posts
Top Foreign Capital Trends across the Middle East Economy
Key Stock Capital Strategies for Regional Growth
Dynamic Middle East Equity Market Cycles to Watch