All Categories
Featured


Key Stock Market Insights for Regional Growth
Table of Contents
Threats are slanted to the downside. In case of an extended conflict, the present effects on the area will be compoundedthrough elevated energy and food costs, declining trade, tourism and remittances, increased financial pressures, and displacement. "The existing crisis is a stark pointer of the work ahead for the region: not only to weather shocks, but to reconstruct more resistant economies with stronger macroeconomic fundamentals, innovate and enhance governance, invest in facilities, and enhance employment-creating sectors," stated.
With peace and the ideal action, countries can develop the institutions, capabilities and competitive sectors that create opportunities for individuals." With this long-term vision in mind, the report takes a close take a look at the area's capacity for commercial policy government actions to increase tactical business activity as a driver of financial development and task creation.

Federal governments in the area have adopted commercial policy at a high rate in the last decade, often through sovereign wealth funds and state-owned enterprises, but the outcomes have actually been mixed. The report highlights the vital requirement for strong institutions and careful targeting of policies. "As nations face the heavy toll of the present conflict, it is essential to likewise not forget the work needed for lasting peace and success," said.
Optimizing Wealth Diversification for a 2026 Economy
Q2 2026: The ICAEW Economic Update Middle East, is a quarterly economic forecast for the region prepared directly for the financing profession. The GCC economy faces a marked contraction this year pending details of the US-Iran contract to end the war. We expect energy flows, tourist and financier sentiment to gradually normalise as war interruptions subside.
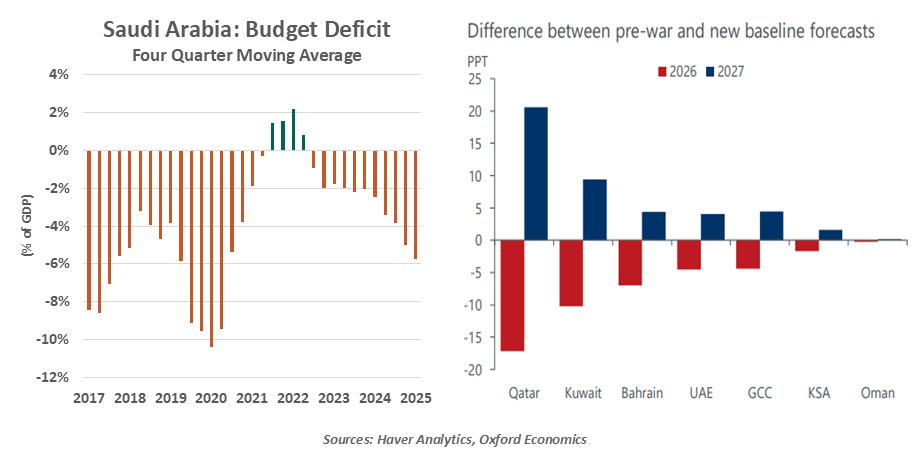
The interim arrangement between the US and Iran is a significant action towards reaching a full-blown offer. A full return to normality in the Strait of Hormuz will likely require time, however the threat of a recession-inducing oil cost spike has decreased. Global GDP is anticipated to grow by 2.4% this year, 0.2 ppt less than we forecasted 3 months ago, and 3.1% in 2027.
Portfolio Diversification Tactics for a Global EconomyWe anticipate a 4.1% contraction in Middle East GDP this year (versus predicted 3.6% growth before the war), greater than the decrease in the first year of the Covid pandemic. Kuwait, Iran, Iraq and Qatar stick out as the hardest hit, owing to their inability to avoid the interruption to regional shipping, war-driven facilities damage and tourist losses.
Our 2026 outlook for the GCC is weaker than 3 months ago, with GDP projection to agreement by 2.4% compared to a 0.2% decline forecasted previously. We anticipate Oman and Saudi Arabia to be the least negatively impacted by the fallout from the conflict, with both economies continuing to broaden this year.
The economic damage incurred in the last few months is substantial. Saudi GDP information for Q1 revealed development slowed to 3% y/y, with non-oil activities broadening by 2.9%, the weakest pace given that the Covid pandemic. On a seasonally changed basis, GDP contracted 1.2% q/q, driven by a 6.8% fall in oil activities as the Strait of Hormuz disruption struck late in the quarter.
GCC Equity Trading Trends for 2026
Aside from Oman, all GCC producers in addition to Iran and Iraq have suffered substantial oil and gas production losses because the start of the conflict. Might data show regional production almost cut in half from pre-war levels, with the decline deepening relative to March and April. Rerouting efforts, consisting of by Saudi Arabia through the East-West Pipeline and the UAE through the Habshan-Fujairah pipeline, have assisted prevent an even bigger plunge in output.
However, we anticipate GCC oil sector output to contract by 14.5% this year, which will mark the steepest decline in numerous years. We then anticipate a 23.5% rebound next year, driven mainly by normalisation from a seriously depressed base. Meanwhile, oil costs have actually been volatile, relieving below $85 per barrel as the interim agreement was announced.
In the medium term, we anticipate oil rates to be a little lower than our pre-war baseline, as the UAE's departure from OPEC+ enables a progressive boost in its output towards the 5mn barrel per day production target as soon as trade normalises. Against this backdrop, the UAE will accelerate the building of a brand-new West-East pipeline that ought to double the capacity of export through Fujairah.
The May PMI studies reported output growth reaching its greatest level in three months, driven mostly by enhanced domestic demand. They stay listed below long-run averages, with weak export orders and rate pressures from higher product and transportation costs are a common style. In general, we anticipate a 1.1% contraction in GCC non-energy sectors this year (compared to 4.2% growth pre-war) and a gradual recovery over the remainder of the decade.

Latest Posts
Top Foreign Capital Trends across the Middle East Economy
Key Stock Capital Strategies for Regional Growth
Dynamic Middle East Equity Market Cycles to Watch